See received payouts together
Use the transactions available from your connected accounts to review received income and spending, rather than relying on one payout notification.
Ulsa for gig and delivery workers
Payouts may arrive at different times, while the costs of working continue. Build a personal spending plan that distinguishes money received from money already needed elsewhere.
For adults with UK bank accounts. Available now on iPhone.
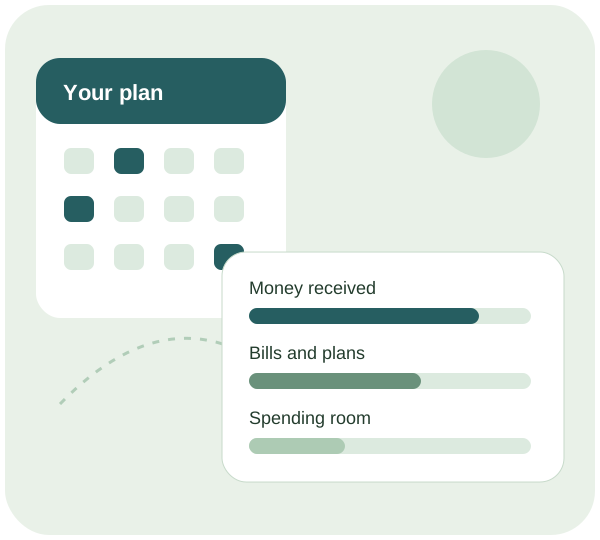
Make room for real life
Use the transactions available from your connected accounts to review received income and spending, rather than relying on one payout notification.
Travel, equipment and other obligations can affect what is available for personal spending. Check them separately instead of treating gross receipts as spare money.
Make a new check when payments arrive or work costs change. A busy week does not establish what the next one will bring.
Safe to spend, explained
Safe to spend uses available account data and included bills and plans. It cannot calculate every business cost or tax obligation, so it is an estimate to review rather than a measure of profit.
Treat the figure as an estimate. Missing transactions, a delayed bank update or a changed bill can alter it. Check what is covered before relying on it.
Read the safe-to-spend guideUlsa connects to supported UK banks through a regulated Open Banking provider. Ulsa cannot move your money or see your bank passwords. You choose whether to connect, and you can disconnect access.
How the bank connection worksHow your data is usedNo platform integration is promised here. This page describes reviewing the bank transactions made available through your connected UK bank accounts.
Not necessarily. Work costs, bills and other obligations may still need covering. This guidance does not calculate profit or tax; review those separately.
Ulsa connects to UK banks through a regulated Open Banking provider with your permission. The connection is read-only: Ulsa cannot move money or see your bank password. It is available on iPhone, with Android coming soon.
A useful next read
A gig work budget connects completed jobs, platform statements and bank receipts without counting the same money twice. It also distinguishes work costs, household commitments and uncertain payments. Employment status and tax records add context, but a budget alone cannot settle either a tax liability or workplace rights.
A freelancer's personal budget connects household commitments with money actually available from the business. Invoices, profit and bank receipts describe different things. Understanding those differences helps explain payment gaps, business costs and tax timing without treating every client payment as immediately available for personal spending.
A bank balance shows an account position, while spending money depends on commitments and timing. Check what the balance includes, allow for bills and essentials, and avoid counting pending payments or transfers twice. The remainder is a working estimate that needs reviewing as circumstances change.
Start with a clearer view
Review your connected spending and build a plan around your commitments.
See plans and featuresThis page is general information, not financial advice.